5 Mistakes to Avoid When Buying Your First Home in Northwest Indiana
Realest · Buying your first home · Northwest Indiana
Before buying your first home in Northwest Indiana, avoid five mistakes: budgeting for only the loan payment, changing your credit before closing, skipping property due diligence, assuming an address proves school eligibility, and losing track of financing or contract deadlines.
By Realest. Research checked November 7, 2026.
Picture the moving boxes after the keys are yours. Now put that picture aside long enough to read the tax estimate and the inspection clause. The house can look right while the paperwork still needs work.
We’re the shop on South Main in Crown Point. Our advice for a first purchase in Lake or Porter County starts with the things you can check before moving day. You do not need to know every mortgage term. You do need to know which questions are still unanswered.
1. Shopping by the loan payment instead of the whole month
A mortgage calculator can make a house look affordable while leaving out costs you will still pay. Start with principal and interest, then add taxes, insurance and mortgage insurance if it applies. Add association dues, utilities and a maintenance allowance outside the loan payment when they are not included.
Cash to close is another line, not a second name for the down payment. The Consumer Financial Protection Bureau’s Loan Estimate explainer separates projected payments, closing costs and estimated cash to close. Ask the lender to walk through those sections with you. Compare written estimates for the same kind of loan and similar assumptions, including points and lender credits.
In Indiana, do not copy the seller’s tax bill into your budget and stop there. Ask which assessment and payable years the estimate uses. Confirm which deductions could apply to you. A deduction reduces taxable assessed value. It is not a promise that your monthly payment will match the seller’s.
Indiana DLGF’s deductions and credits guidance directs eligibility and filing questions to the county auditor. Use the office for the county where the property actually sits. A new build also deserves a completed-home tax estimate, not a budget built around an earlier vacant-lot bill.
Before the next showing, write down your comfortable total monthly housing cost and the cash you want left after closing. Ask the lender what is missing from its estimate. The purchase price is only one part of that conversation.
2. Financing the furniture before the house closes
The sofa can wait. A new account or financed purchase can change the financial picture your lender is still reviewing. A preapproval does not give every later purchase a free pass.
The CFPB’s Your Home Loan Toolkit warns that even financing a refrigerator before closing could make getting a mortgage harder. That does not mean every credit inquiry cancels a loan. It means you should ask your loan officer before taking on debt rather than letting the lender discover it later.
Talk through proposed job changes, unusual deposits or transfers, and any change in the money you plan to use. Keep the records the lender requests. Do not move money around just to make a statement look simpler. Documentation matters more than a tidy screenshot.
Keep paying existing obligations on time. If something changes, tell the lender promptly. Hiding a problem gives everyone less time to understand it.
Before you buy anything on credit, ask, “Will this change my qualification, documents or closing timing?” Get an answer about your loan, not a rule borrowed from someone else’s purchase.
3. Treating an appraisal or a fresh coat of paint as an inspection
An appraisal and a home inspection do different jobs. The appraisal helps the lender evaluate value. An independent inspector evaluates the home’s physical condition. Neither a listing description nor a brief tour does that work for you.
The CFPB recommends scheduling an independent inspection early so there is time to understand findings and arrange follow-up. Ask the inspector what is included, what is excluded and whether a specialist should evaluate an issue. A general inspection does not answer every question about a sewer line, private water system or drainage problem.
For a Lake or Porter County property, confirm the actual utility arrangements before choosing your inspection scope. Ask about water entry, roof age, heating equipment and past work. Request the documents behind a repair claim. Discuss available permit records with the authority that serves the address.
Read the inspection clause before deciding what protection to keep or waive. A right to request repairs or terminate comes from your agreement and applicable law, not from this article. A seller is not automatically required to fix everything an inspector finds.
Before the inspection window runs out, separate the findings into questions, estimates and decisions. Discuss them with your agent while there is still time to give any required notice.
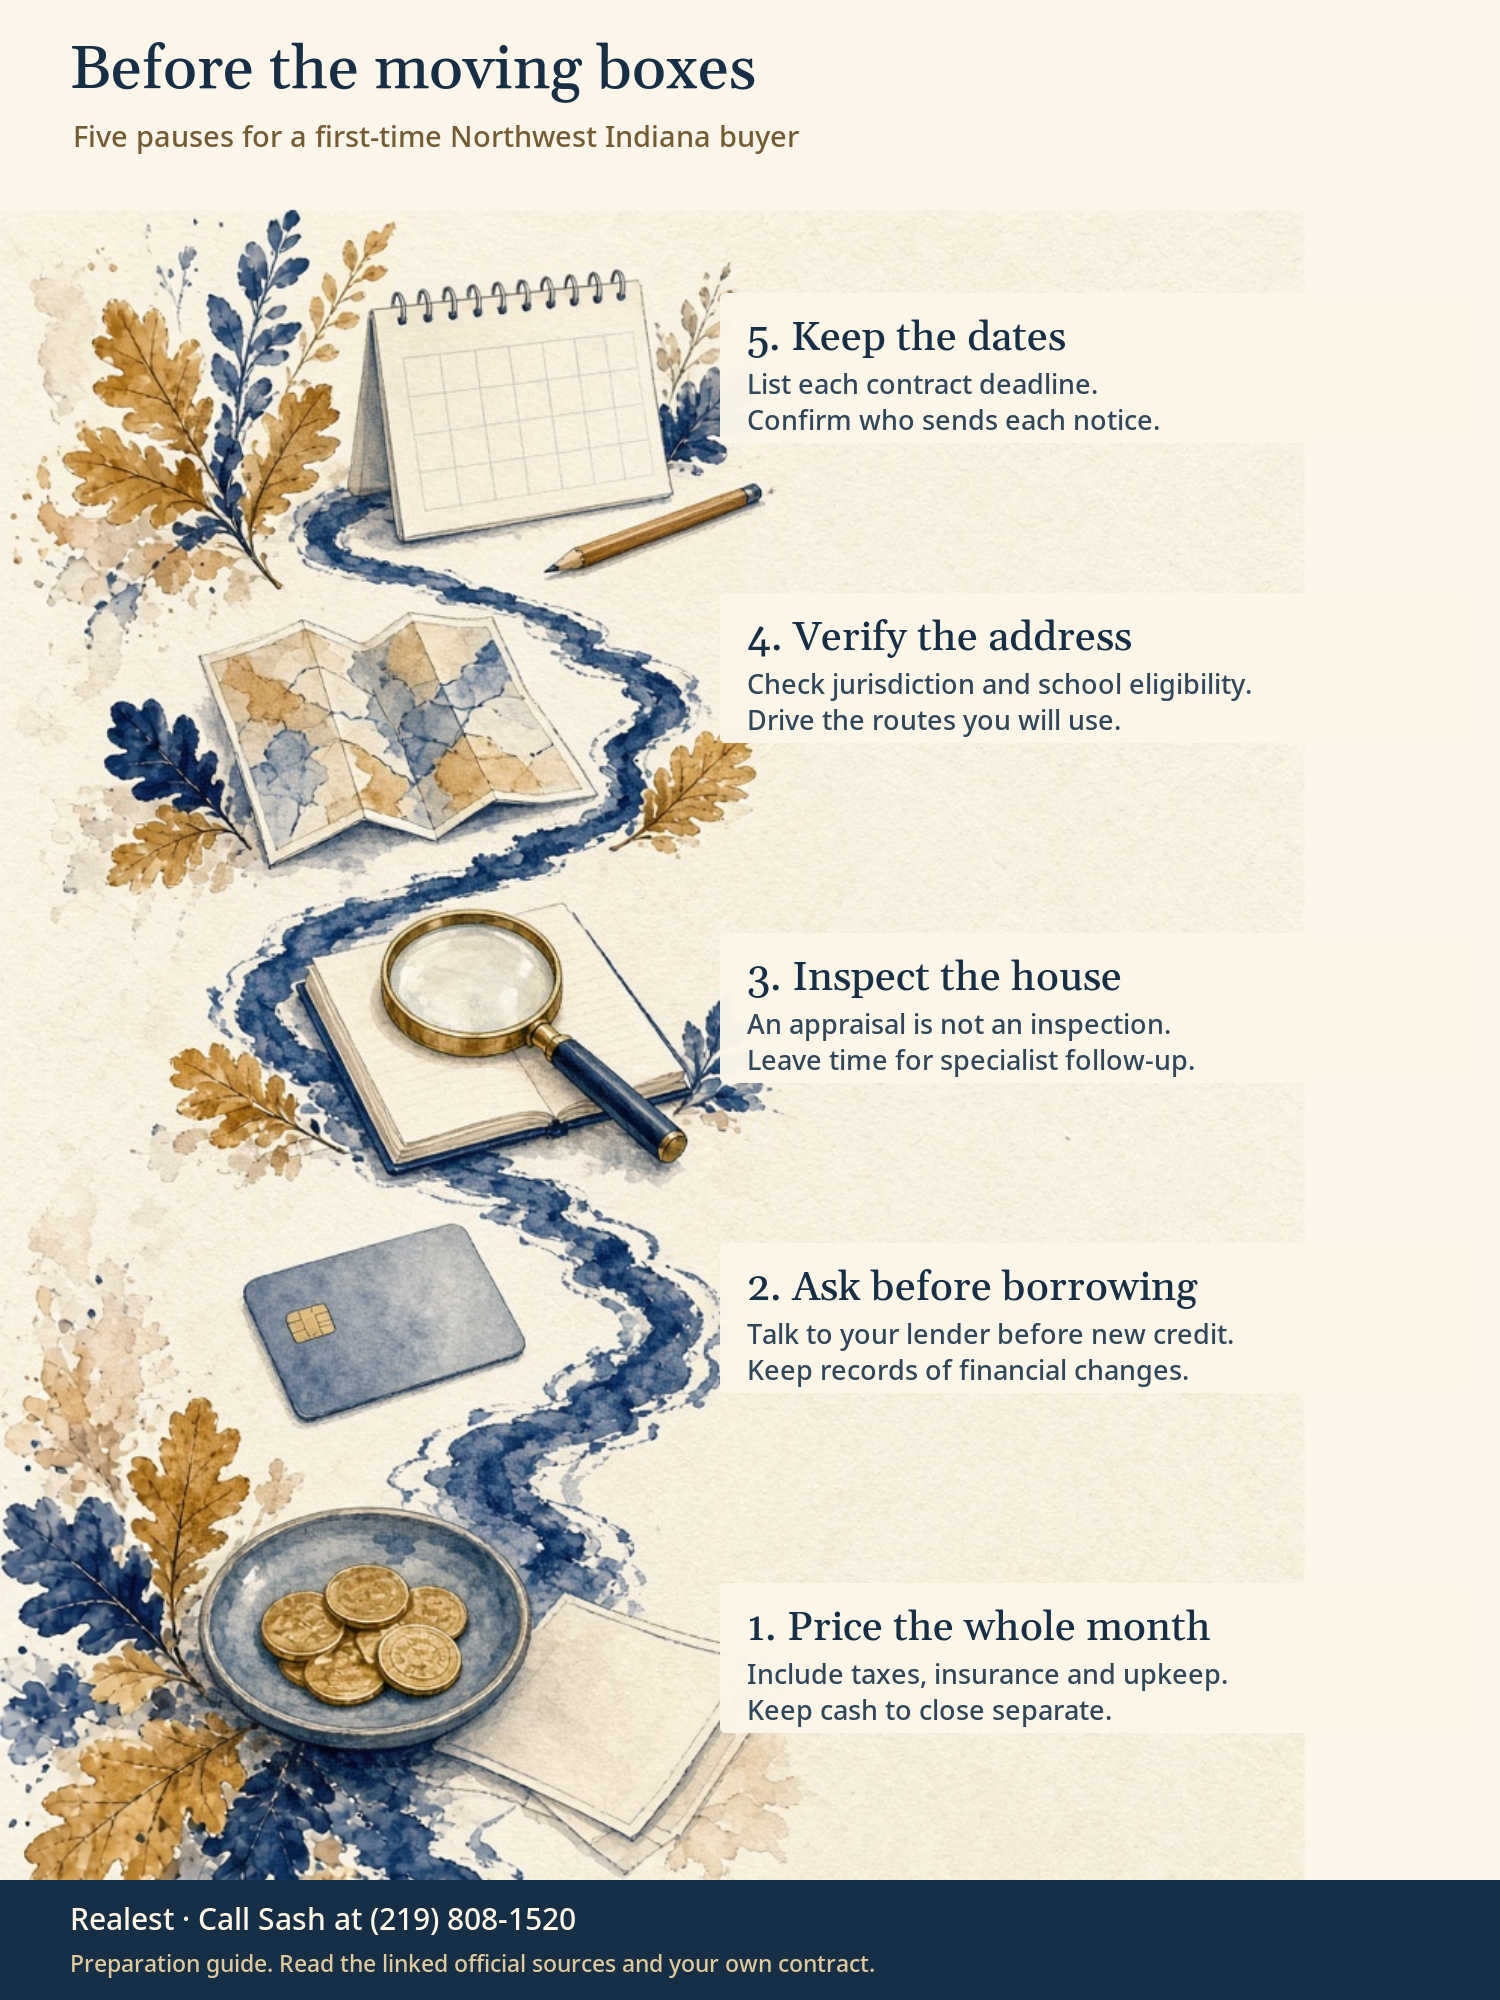
4. Letting a town name answer questions it cannot answer
A postal address helps mail arrive. It does not settle every question about municipal services, school eligibility or the department that handles permits. Look up the particular property instead of extending one listing’s details to the next house.
For example, Crown Point Community School Corporation’s enrollment page says students must live within its district and links an address eligibility tool. That is a better starting point than a school name in a listing. Confirm the serving corporation, assigned schools and enrollment documents directly. If another corporation serves the address, ask that district.
We do not promise placement or future boundaries. We also do not rank neighborhoods by who lives there. Tell us the housing features and routes you need, and use the relevant school corporation’s information for school questions.
Then test the routine outside the house. Drive to work at your usual departure time. Check the trip to the places you use each week. A map’s distance and your actual trip are different things.
If Crown Point is on your list, our Realest.net Crown Point resource and the RealEstateUSA moving guide give town context. Use them to prepare questions, then confirm the answers for the home you want.
Before you assume anything based on the address, name the office or district that can answer it. Keep the answer with the property notes.
5. Remembering closing day and forgetting the dates before it
A signed agreement can start several clocks. Inspection, financing, appraisal and notice obligations depend on the contract you sign. Do not replace those dates with a general idea that “we close next month.”
Make a short deadline list with your agent. Include what must happen, who is responsible and what notice is required. Ask whether a date uses calendar days or another definition in the agreement. If a lender or inspector needs more time, discuss the issue before the deadline. A requested extension is not the same as a signed extension.
For most mortgages, you must receive the Closing Disclosure at least three business days before closing. Read the CFPB’s closing-document guidance and ask your lender how delivery and timing apply to your loan. That disclosure review period is separate from your purchase agreement’s other deadlines.
Compare the Closing Disclosure with the latest Loan Estimate. Ask about changes in loan terms, cash to close and charges you do not recognize. Verify any wiring instructions by calling a known, independently verified number. Do not rely on a last-minute email announcing a different bank account.
Before you book movers or deliveries, confirm the closing and possession arrangements with your agent. The date on a calendar is not confirmation that every condition has been satisfied.
First-home questions we want you to ask
What costs should a first-time buyer budget for besides principal and interest?
Include property taxes, homeowners insurance, mortgage insurance when applicable, association costs, utilities and maintenance. Track the down payment, closing costs and other cash needed before closing separately.
Can opening a credit account affect a mortgage before closing?
Yes. New borrowing can affect the financial information a lender uses to approve the loan. Ask your loan officer before financing purchases or opening credit, and report changes rather than assuming a preapproval covers them.
Is an appraisal the same as a home inspection?
No. An appraisal helps the lender evaluate value. An independent inspection evaluates the home’s physical condition. Discuss inspection scope, specialist follow-up and contract deadlines before you commit.
Does a mailing address confirm a school assignment?
No. Confirm the exact address with the serving school corporation and ask about assigned schools and enrollment requirements. A postal city, ZIP code or listing remark does not establish eligibility.
What happens if an inspection or financing deadline is missed?
The consequences depend on the purchase agreement and circumstances. Review notice requirements with your agent and, when needed, an attorney before the deadline. Do not assume a pending inspection or lender review automatically extends the contract.
Bring the questions before you bring the boxes
You can like a house and still take time to understand the payment, condition and agreement. Our job is to help you put the questions in the right order and know when a lender, inspector, district or attorney needs to answer.
Call Sash with the home you are considering, your timing and the part you want explained. We can start there.
Call Sash at (219) 808-1520 saso@realest.com
Realest · 112 S. Main St., Suite B · Crown Point, IN 46307Love Thy Neighbor.
General buying guidance, not individual legal, tax or lending advice. Your property, loan and agreement need their own review. No loan approval, school placement or property value is guaranteed.
Categories
- All Blogs (102)
- buyers (7)
- commercial (2)
- Community & Lifestyle (24)
- first time buyers (12)
- Home Buying Tips (13)
- Home Selling (4)
- homebuyers (12)
- Homeownership & Maintenance (4)
- Join Realest (5)
- Listings (16)
- Local Market Insights (18)
- real estate (12)
- real estate agent (14)
- Real Estate Investing (2)
- Real Estate News & Trends (5)
- sellers (6)
- selling (3)
Recent Posts